Stock Analysis
Reddit (RDDT) Crashes ~30% After a Q3 Beat on a Google AI Search-Traffic Warning
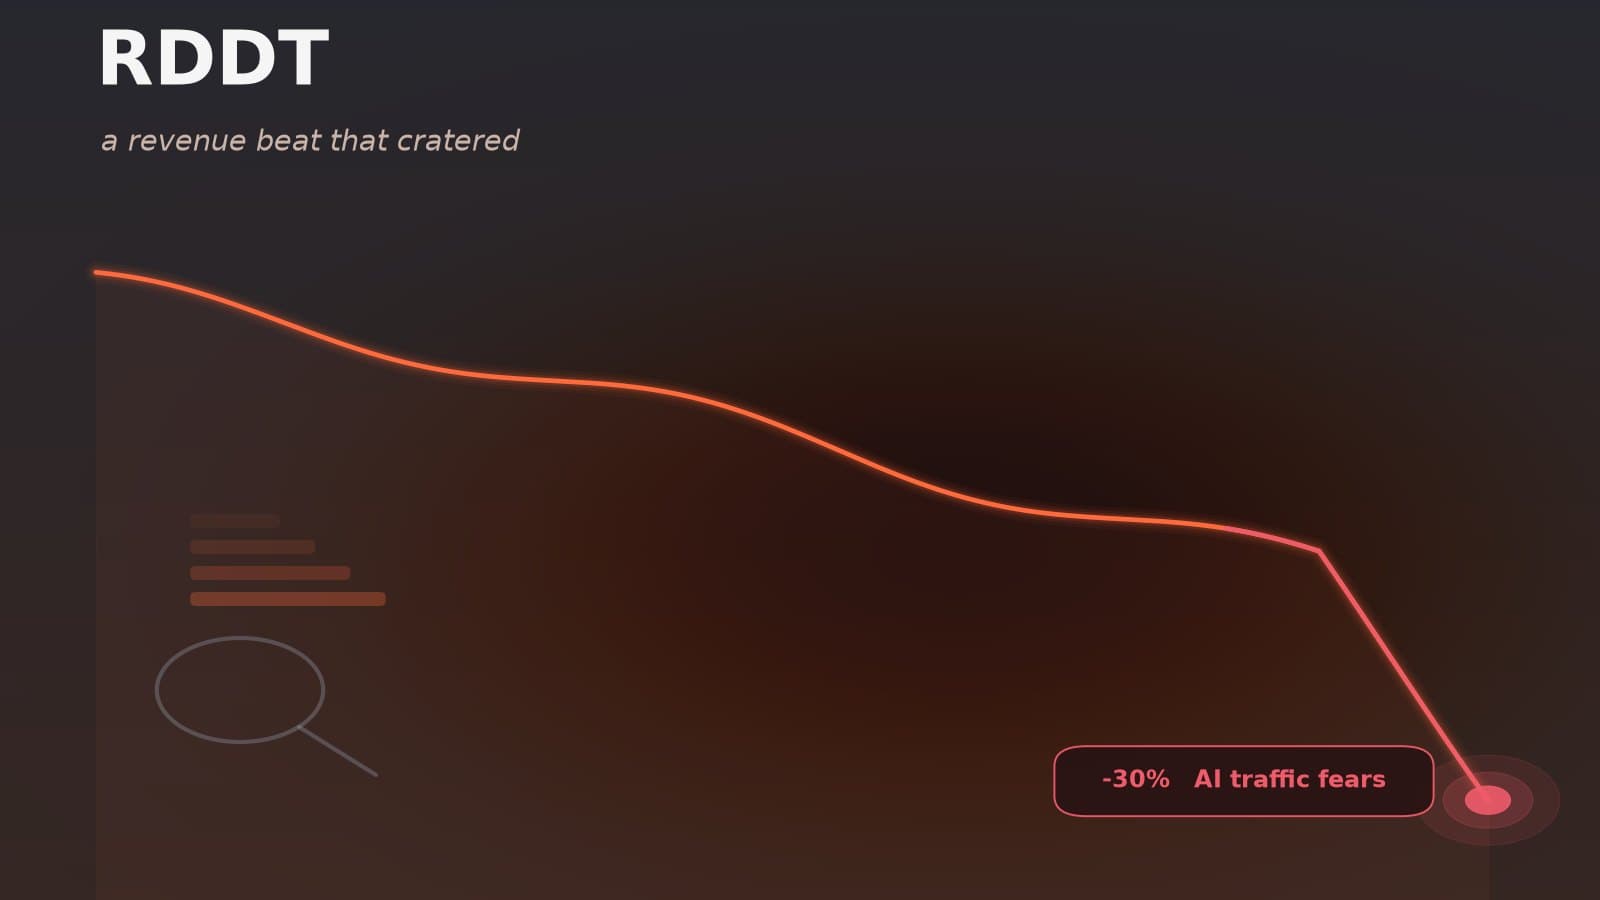
Reddit crashed about 30% to roughly $90.79 on October 30 — a striking reaction, because the quarter itself was strong: revenue of $895 million rose 53% year over year, a clear beat, with net income of $283 million, diluted EPS of $1.40 and adjusted EBITDA of $402 million. The stock cratered on what management said about the future. On the earnings call, CEO Steve Huffman warned that search referrals fell more than a million per week on average in October as Google answers more queries with AI, and that daily active users (around 130 million) could fall a low-double-digit percentage in the fourth quarter if the trend held. Investors also fixed on a 2% year-over-year decline in US daily actives — Reddit's most valuable market, where revenue per user is more than five times the international level — and on fourth-quarter revenue guidance of $1.00–$1.03 billion that came in below expectations; Citizens downgraded the stock before the open. The one bullish counterweight was monetization: revenue per user still jumped 36% globally. The move was company-specific — Reddit's roughly 30% drop was about four times the moves of social peers Snap and Pinterest (each down ~7%), on a day the broad market fell about 2%. After the crash Reddit trades at roughly 14 times forward earnings with about $3 billion of net cash — not expensive for 50%-plus growth, if the growth is durable. The whole debate is whether rising revenue per user can keep outrunning a top of the funnel that AI search is draining.
Why Reddit stock crashed — a revenue beat the market hated
On Friday, October 30, 2026, Reddit (NYSE: RDDT) crashed about 30%, trading near $90.79 intraday after gapping lower at the open and sliding to a fresh 52-week low around $90 [1]. What makes the move jarring is that the quarter itself was strong: Reddit reported third-quarter revenue of $895 million, up 53% year over year, a clear beat, with GAAP net income of $283 million, GAAP diluted EPS of $1.40, and adjusted EBITDA of $402 million at a fat 44.9% margin [2]. Revenue was led by advertising of $847 million, up 54%, and the company generated roughly $363 million of free cash flow — on the trailing numbers, the operating business was firing. This was not a weak print punished by the market; it was a good print obliterated by what management said about the future — specifically, that Google's shift to AI-generated answers appears to be draining the search traffic Reddit depends on to grow its audience.
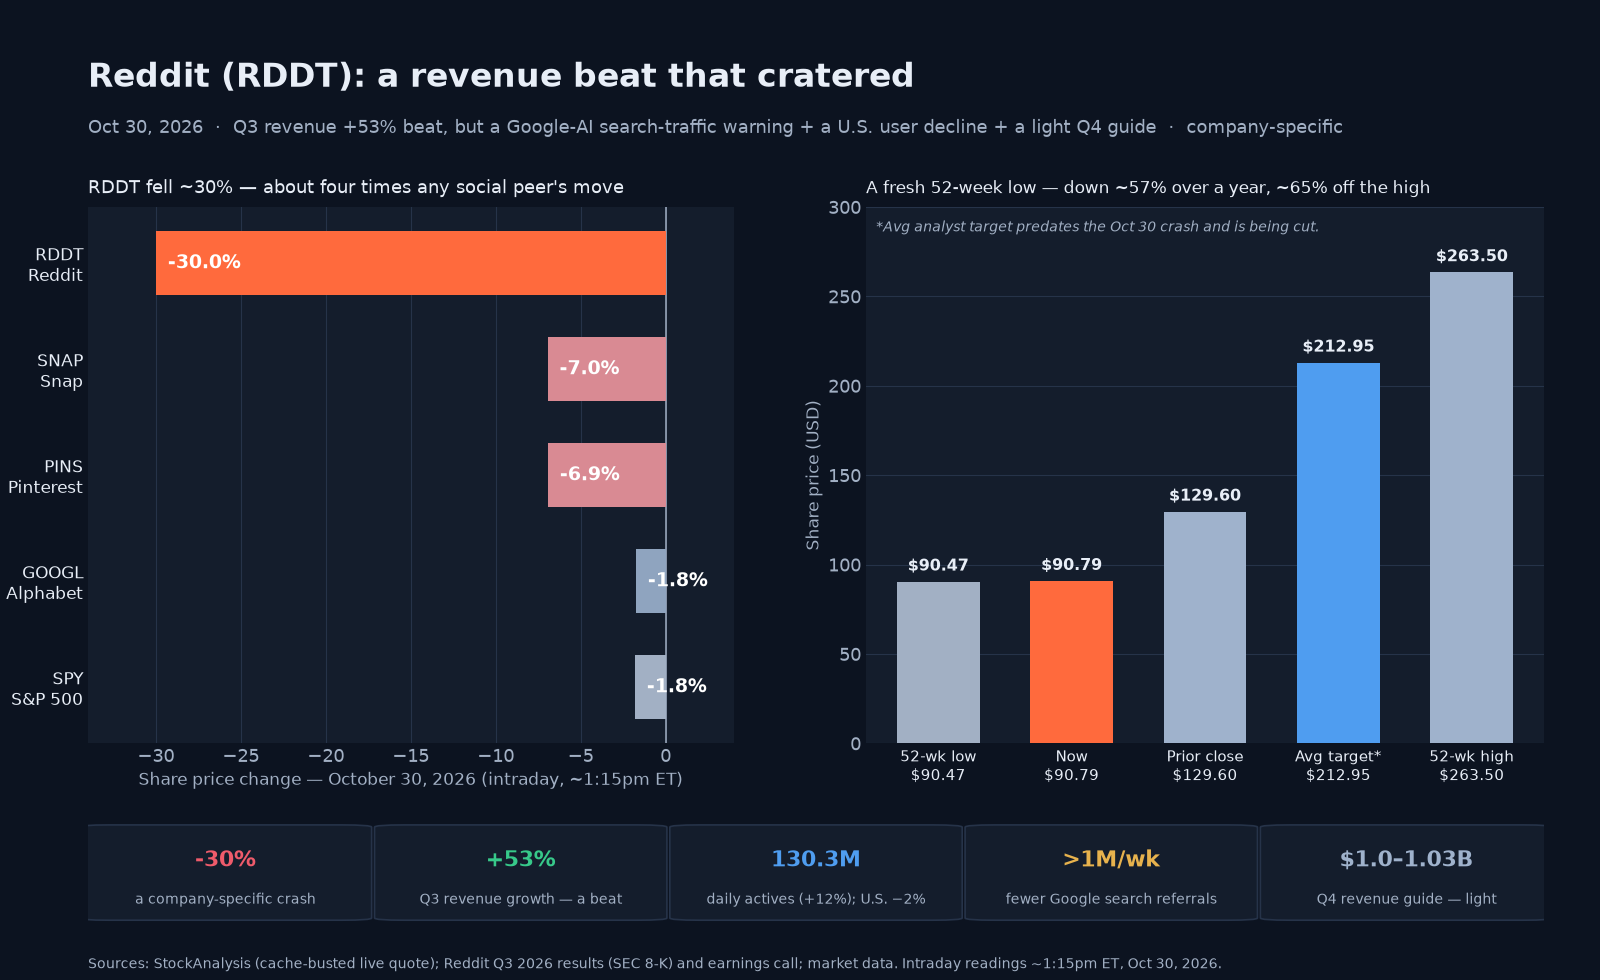
The scale of the damage is easier to feel in the chart than the numbers. Reddit is now down roughly 57% over the past 52 weeks and about 65% from its high near $263, and Friday's plunge took it to a brand-new 52-week low — all for a company that just grew revenue more than 50% [1]. A stock does not fall a third of its value on a revenue beat unless investors have concluded that the growth algorithm itself is in question. That is exactly what happened here.
What actually spooked investors — the traffic warning, not the quarter
The trigger was a warning on the earnings call. Chief executive Steve Huffman told analysts that Reddit's search referrals fell by more than a million per week, on average, in October, and cautioned that daily active users — around 130 million — could decline by a low-double-digit percentage in the fourth quarter if that trend continued [2]. Management pointed to the changing shape of Google search as the leading suspected cause: as Google answers more queries directly with AI Overviews and its AI Mode, users click through to source sites like Reddit far less often. Huffman framed this as a hypothesis rather than a proven mechanism — Reddit cannot see inside Google's ranking and referral systems — and also cited lower Google rankings for Reddit's machine-translated pages, particularly outside the United States, as a contributor; he said the AI-search shift appeared to be the larger factor [2]. Reddit is unusually exposed because a large share of its logged-out, top-of-funnel traffic arrives from Google — the very channel that feeds new users into the platform. The irony is sharp: Reddit licenses its content to help train AI models — and said renewal talks with Google and OpenAI are ongoing, with no new deal announced — yet that same class of AI is now intercepting the clicks that brought it an audience.
The second blow was in the user numbers themselves. Global daily active uniques rose 12% to 130.3 million, but the detail investors fixated on was the United States: daily actives there fell about 2% year over year to 50.7 million (and declined roughly 5% from the prior quarter) [2]. That matters disproportionately because the US is Reddit's cash engine — US average revenue per user is about $13.82, more than five times the $2.43 Reddit earns internationally [2]. International daily actives grew 24% to 79.6 million, but those users monetize far less. One nuance tempers the alarm: the US decline was concentrated in logged-out visitors (down about 4%), while US logged-in users — the audience Reddit actually monetizes — rose about 1%, and management says app and logged-in users drive more than 80% of monetization [2]. So the erosion is real but sits mostly in the less-valuable, casual-visitor segment, which softens the threat to the revenue math without removing it. Third, the fourth-quarter guidance — revenue of $1.00–$1.03 billion and adjusted EBITDA of $480–$510 million — landed below Wall Street's expectations, about 3% under the roughly $1.05 billion consensus at the midpoint, though it still implied roughly 40% year-over-year revenue growth; attaching a below-consensus guide to a user-decline warning gave the market everything it needed to sell [2]. Brokers moved fast: before the opening bell, Citizens cut the stock to Market Perform and KeyBanc downgraded it to Sector Weight, both citing the US daily-active decline and worsening search-referral trends [2].
The one genuinely bullish fact fighting the tape was monetization. Average revenue per user still jumped 36% globally, to $6.87, with the US up 53% — proof that Reddit is extracting far more from each user through better ad products and its data-licensing business [2]. The whole debate now reduces to a single question: can rising revenue-per-user keep outrunning a top of the funnel that AI search is quietly draining? For one quarter, monetization won on revenue but lost on the stock. The market decided the traffic risk is the story.
The valuation question
After a fall this steep, Reddit no longer looks like the momentum darling it was a year ago. On the numbers it now trades around 18.5 times trailing earnings and roughly 14 times forward earnings, at about 5.6 times trailing sales, with a balance sheet carrying roughly $3 billion of cash against almost no debt [3]. For a business compounding revenue above 50% with gross margins near 91% and adjusted-EBITDA margins in the mid-40s, that is not an expensive multiple — if the growth holds. (Those adjusted-EBITDA margins exclude sizable stock-based compensation — around 15% of revenue — so GAAP profitability is thinner than the adjusted figure suggests.) And that "if" is the whole point. The market is no longer paying a premium for Reddit's growth because it is no longer sure the growth is durable: a platform whose user acquisition depends on a channel that is actively shrinking cannot be valued like one whose funnel is intact. The de-rating from a high near $263 to about $91 is the market repricing the quality of the growth, not just its pace.
Why it matters
Reddit is the clearest public test case yet of a fear that hangs over the entire open web: that generative AI search answers questions so well that users stop clicking through to the sites that supplied the answers. For a content platform whose audience growth is tied to Google referrals, that is not an abstract risk — it is a direct hit to the top of the funnel, and this quarter produced the first concrete numbers showing it. The read-through rippled across social and content peers on the day, with Snap and Pinterest each down around 7% as investors extended the user-growth worry, even as the broad market fell only about 2% [5]. But the gap in magnitudes is the point: Reddit's roughly 30% drop was about four times any peer's, which marks this as a company-specific repricing driven by Reddit's own disclosure, not a sector-wide verdict [5]. The episode also shows how quickly the market will strip the growth premium from a stock once it doubts the growth is durable — a 53% revenue beat was not remotely enough to offset a credible threat to the user base. How Reddit responds — building traffic it owns rather than rents — will shape not just its own story but how investors price every business that depends on Google for discovery.
The move, in one cross-section
The same-session tape shows a company-specific crash with a modest social read-through, on a broadly weak day [5]:
| Name (ticker) | Oct 30, 2026 (intraday) | Read-through |
|---|---|---|
| RDDT — Reddit | ≈−30% | The earnings name — crashed on a Google-AI traffic warning, a US user decline and a light Q4 guide, despite a revenue beat [1][2] |
| SNAP — Snap | ≈−7.0% | Social peer — down on the shared user-growth/AI-referral worry, but a fraction of Reddit's move [5] |
| PINS — Pinterest | ≈−6.9% | Social peer — similar read-through, far smaller magnitude [5] |
| GOOGL — Alphabet | ≈−1.8% | The AI-search actor at the center of Reddit's warning — down only modestly [5] |
| SPY — S&P 500 (ETF) | ≈−1.8% | Broad market lower on a risk-off day — Reddit's drop was far larger [5] |
Reddit down about 30% while social peers fell mid-single digits and the market dropped roughly 2% is the signature of a company-specific catalyst — here Reddit's own results and its traffic warning — layered on a weak tape [5].
What the Street thinks
Coming into the report, Wall Street was firmly bullish: a Buy consensus from more than 30 analysts, with an average 12-month target near $213 and a range from about $130 to $300 [6]. But those figures were set before Friday's crash and before the traffic warning, so they are stale almost by definition — Citizens cut its rating before the open, and more downward revisions are likely as analysts re-model the user trajectory [2][6]. The useful signal is not the headline target but the direction of travel: even the lowest pre-crash target, around $130, sits well above the roughly $91 the stock now trades at, which tells you how far the Street's assumptions have to fall to meet the new price [6]. The real question for analysts now is whether to treat the Google-AI referral decline as a one-time reset or a structural impairment — and that choice, not the old targets, will drive where estimates land.
What to watch
- US daily active users. The single most important number next quarter — whether the US audience stabilizes or keeps shrinking in Reddit's highest-value market [2].
- Search-referral trends. Whether the October drop in Google referrals (more than a million a week) deepens, stabilizes, or is offset by traffic Reddit drives through its own app and logged-in engagement [2].
- Revenue per user versus users. Whether monetization (up 36% globally) can keep outrunning a flat-to-shrinking audience — the core tension in the story [2].
- Reddit's login strategy. Reddit plans to test a logged-in-only experience in some markets outside the US in the fourth quarter — a bid to lessen its dependence on Google referrals, sharpen ad targeting and curb AI scraping, at the risk of losing casual reach [2].
- Analyst revisions. How far targets and estimates are cut from their stale, pre-crash levels. Moves are tracked on the Reddit stock page [6].
Illustrative scenario sensitivity
Because the crash is a reaction to traffic durability rather than the quarter just reported, the scenarios below are anchored to whether Reddit can grow through the Google-AI referral decline rather than to a single valuation [6]. They are a descriptive, author-weighted exercise over roughly the coming six-to-twelve months as the user trajectory clarifies — not a forecast, target, recommendation, or trading advice — with subjective weights that sum to 100%.
| Scenario | Illustrative price | Weight | Key drivers |
|---|---|---|---|
| Traffic stabilizes, monetization compounds | ~$130 | 25% | The search-referral hit proves manageable, US users stabilize, and 36%-plus revenue-per-user growth plus international scale restore confidence in durable growth, re-rating the stock toward the low end of pre-crash targets [6]. |
| Cheap, but the overhang lingers | ~$95 | 45% | Revenue keeps growing but the US user decline and AI-referral worry cap the multiple; the stock stays cheap and range-bound near current levels while the market waits for proof [1]. |
| AI search structurally impairs the funnel | ~$65 | 30% | Google referrals and US daily actives keep falling, revenue growth decelerates sharply, and the market re-rates Reddit as a lower-growth platform, compressing the multiple further [2]. |
Weighting those (0.25 × $130 + 0.45 × $95 + 0.30 × $65) gives an author-weighted reference value near $95 — an illustrative, probability-weighted scenario output mechanically derived from the weights above, and not a price target, fair-value estimate, or prediction — a touch above Friday's ~$90.79 intraday price [1][6]. The slight premium reflects a business still growing fast with strong margins and net cash, offset by a genuine, hard-to-size threat to its user funnel; the wide dispersion between the scenarios is the honest signal that the outcome hinges on traffic durability far more than on this one strong quarter. This is a scenario exercise and descriptive analysis of a news-driven move, not investment advice.
Reddit data snapshot — October 30, 2026
| Figure | Value | As-of / source |
|---|---|---|
| Intraday quote | ~$90.79 (−~30%) — an intraday reading (the session was open); gapped down from the open and fell to a fresh 52-week low near $90 | Fri, Oct 30, 2026, ~1:15pm ET — StockAnalysis [1] |
| Prior close / open | $129.60 prior close; opened ~$100.25; had already slipped ~5% into the report | Oct 30, 2026 [1] |
| 52-week trend | 52-week range $90.47–$263.50; down ~57% over 52 weeks and ~65% off the high; beta ≈2.05 (high) | As of Oct 30 [1] |
| Market cap | ≈$17.45B (≈192.4M shares); enterprise value ≈$14.45B; ~$3.0B cash against ~$31M debt (net cash ~$3B) | Oct 30 — StockAnalysis [3] |
| Valuation | Trailing P/E ≈18.5×; forward P/E ≈14×; price-to-sales ≈5.6×; gross margin ≈91.5%, operating margin ≈29.4% — a high-growth, high-margin platform de-rated hard | Oct 30 — StockAnalysis [3] |
| Q3 2026 results | Revenue $895M (+53% YoY, a beat); net income $283M; diluted EPS $1.40; adjusted EBITDA $402M (44.9% margin); DAUq 130.3M (+12%); WAUq 515.2M (+16%); US DAUq 50.7M (−2% YoY); intl DAUq 79.6M (+24%); ARPU $6.87 (+36%; US $13.82, intl $2.43) | Oct 30 — Reddit Q3 2026 results (SEC 8-K) [2] |
| Catalyst | Q3 earnings: a revenue beat that cratered. Despite +53% revenue, the stock fell ~30% on (1) a Google-AI search-traffic warning (search referrals down >1M/week on average in October; Q4 daily actives could fall a low-double-digit % sequentially from ~130M if that trend continued); (2) a US daily-active decline (−2% YoY); (3) a Q4 revenue guide of $1.00–1.03B below Street expectations (though still ~40% YoY growth); and pre-open broker downgrades (Citizens, KeyBanc) | Oct 30, 2026 — company results + earnings call [2] |
| Same-day cross-section | SNAP −7.0%, PINS −6.9% (social peers); GOOGL −1.8%; SPY −1.8% — RDDT's ~30% drop was ~4× any peer, i.e. company-specific | Oct 30 intraday [5] |
| Analyst view | Pre-crash consensus Buy, avg target ~$213 (low ~$130, median ~$205, high ~$300) from 34 analysts — but these predate the Oct 30 crash and are being cut (Citizens already did) | Oct 30, 2026 — StockAnalysis / analyst notes [6] |
Reddit (RDDT) stock FAQ
Why did Reddit (RDDT) stock crash on October 30, 2026?
Reddit fell about 30% to roughly $90.79 even though its third-quarter results were strong — which is the striking part. Revenue was $895 million, up 53% year over year (a beat), with net income of $283 million, diluted EPS of $1.40 and adjusted EBITDA of $402 million. The stock crashed on what management said about the future. On the earnings call, CEO Steve Huffman warned that Reddit's search referrals fell more than a million per week on average in October, as Google answers more queries with AI and sends fewer clicks to source sites, and that daily active users (around 130 million) could decline a low-double-digit percentage in the fourth quarter if the trend continued. Two other things compounded it: US daily active users fell about 2% year over year in Reddit's most valuable market, and fourth-quarter revenue guidance of $1.00–$1.03 billion came in below Wall Street's expectations. Citizens downgraded the stock to Market Perform before the open. In short, a good quarter was overwhelmed by a credible threat to the growth of Reddit's user base.
What does Google's AI search have to do with Reddit's stock?
A large share of Reddit's audience — especially its logged-out, top-of-funnel traffic — arrives through Google search. When someone searches a question and clicks a Reddit thread in the results, that visit can become a new or returning user. As Google answers more queries directly with AI Overviews and its AI Mode, users increasingly get the answer without clicking through, so fewer of them land on Reddit. Management quantified the early impact for the first time this quarter: search referrals down more than a million per week on average in October. Because Reddit's user growth depends on that referral channel, a sustained decline threatens the top of its funnel — which is why the market treated it as a growth-algorithm problem rather than a one-quarter blip. The dynamic is pointed because Reddit also licenses its content to help train AI models, so the same technology it supplies data to is now intercepting some of its traffic.
Wasn't Reddit's quarter actually good?
Yes — on the trailing numbers it was strong, which is what makes the crash notable. Revenue grew 53% to $895 million, beating estimates; adjusted EBITDA was $402 million at a 44.9% margin; and average revenue per user jumped 36% globally to $6.87 (up 53% in the US), showing Reddit is monetizing its audience far more effectively. Global daily active users also rose 12% to 130.3 million. The problem was entirely forward-looking: the warning that AI search is cutting referral traffic, a 2% year-over-year decline in US daily actives (Reddit's highest-value market), and fourth-quarter revenue guidance below expectations. The market concluded that strong current monetization cannot offset a shrinking or stalling user base indefinitely, so it repriced the stock for slower, less certain future growth — a good quarter met with a worse outlook.
Is Reddit stock cheap now after the 30% crash?
It is far cheaper than it was, but 'cheap' depends entirely on whether the growth holds. After losing nearly 60% over the past year, Reddit trades at roughly 18.5 times trailing earnings and about 14 times forward earnings, around 5.6 times sales, with roughly $3 billion of net cash. For a company still growing revenue above 50% with gross margins near 91% and EBITDA margins in the mid-40s, those multiples are not demanding — if the growth is durable. The reason the market stopped paying a premium is precisely the doubt about durability: a platform whose user acquisition runs through a channel (Google search) that is actively shrinking cannot be valued like one with an intact funnel. So the valuation looks reasonable on current growth but reflects genuine uncertainty about whether that growth continues. This is descriptive analysis, not investment advice.
How did Reddit's crash compare with other social-media stocks that day?
The move was overwhelmingly specific to Reddit. On the same day, Snap and Pinterest each fell about 7% as investors extended the user-growth and AI-referral worry across social and content names, and Alphabet — the company at the center of Reddit's warning — was down only about 1.8%, in line with a broad market that fell roughly 2% on a risk-off day. Reddit's roughly 30% drop was about four times any peer's, which is the classic signature of a company-specific catalyst: its own earnings report and traffic warning, not a sector-wide verdict. The modest declines in Snap and Pinterest show the theme resonated beyond Reddit, but the scale of Reddit's fall shows the market saw its specific disclosure — the quantified search-referral decline and the US user drop — as materially worse for Reddit than for its peers.
What should investors watch next for Reddit?
Four things. First and most important, US daily active users — whether Reddit's most valuable audience stabilizes or keeps shrinking, since monetization cannot outrun user declines forever. Second, search-referral trends — whether the October drop in Google referrals deepens or is offset by traffic Reddit drives through its own app, notifications and logged-in engagement. Third, the balance between revenue per user and users — monetization grew 36% globally, so the question is whether that can keep compensating for a flat-to-shrinking funnel. Fourth, analyst revisions: the pre-crash average target near $213 is stale, Citizens already downgraded before the open, and more cuts are likely, so the direction and size of those revisions will signal how the Street is re-modeling the user trajectory. Because the debate is about traffic durability rather than the last quarter, the stock is likely to stay a show-me story until the user numbers prove one case or the other.